Hannah lived in Raleigh. She was 31 with a new baby and a 30 year mortgage. Her husband worked in sales and she freelanced from home. A friend said they needed $1 million of cover. An agent said half of that was enough. She searched for Best Life Insurance for Young Families every night. The answers did not match.
She then listed her debts and her income and her daughter’s future costs. She compared term quotes for the same cover amount. The monthly price surprised her. This guide follows her method for Best Life Insurance for Young Families.
Best Life Insurance for Young Families: Quick Answer
For most young families the best choice is level term life. Pick a term of 20 or 30 years. Choose a cover amount from your income and debts. That is the core of Best Life Insurance for Young Families.
Prices are low when you are young. MoneyGeek lists a 30 year old non-smoking woman at $60 a month. That buys $1 million of cover. A man pays $74. Best Life Insurance for Young Families gets more costly every year you wait.
Why Young Families Need Life Insurance
Life insurance replaces income if a parent dies. It can pay the mortgage and childcare and later college costs. Young families have the most to lose and the least savings. That is why Best Life Insurance for Young Families focuses on large cover.
Term life fits that need. It covers a fixed period at a level price. One 2026 comparison put whole life at ten times the price of term. That was for a healthy 40 year old. Best Life Insurance for Young Families is usually term.
How Much Cover Does a Young Family Need
Three methods are common. The first is 10 times your yearly income. It is quick but rough. The second is DIME. DIME adds Debt and Income years and Mortgage and Education costs. The third replaces the income of each earner.
One guide shows the third method. Two parents earn about $50000 each. It estimates $1.25 million of cover per parent. That assumes a 4 percent investment return. If you cannot afford the full amount then buy what you can. Add more later. Size the cover first when you plan Best Life Insurance for Young Families.
A Worked Example of Cover Amount
Take a family with one earner on $60000 a year. They owe $20000 in loans and $250000 on a mortgage. They want to fund $100000 of college costs. The income need runs 15 years until the child is independent. The table shows the result.
Best Life Insurance for Young Families: Cover Amount Example
| Component | Amount |
|---|---|
| Debt (loans) | $20000 |
| Income for 15 years | $900000 |
| Mortgage | $250000 |
| Education | $100000 |
| DIME total | $1270000 |
| 10 times income rule | $600000 |
The two methods differ by more than double. DIME ignores savings and investment growth. Subtract savings and group cover from the DIME total. The real need often sits between the two figures. Use both when you shop for Best Life Insurance for Young Families.
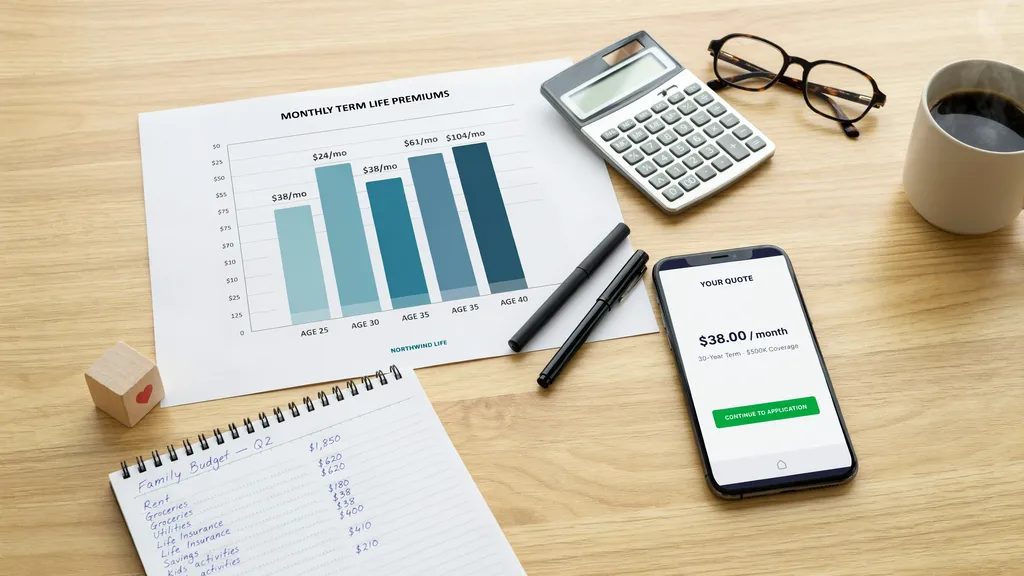
What Term Life Costs by Age
The table shows average monthly prices from MoneyGeek. They come from quotes from 21 carriers and were updated on 1 November 2026. They are for non-smokers in average health with a 20 year term. Your quote will differ.
Best Life Insurance for Young Families: Monthly Term Cost by Age (20 Year Term)
| Age | Woman $500000 | Woman $1 million | Man $500000 | Man $1 million |
|---|---|---|---|---|
| 25 | $30 | $54 | $32 | $67 |
| 30 | $32 | $60 | $38 | $74 |
| 35 | $37 | $68 | $47 | $85 |
| 40 | $47 | $86 | $59 | $109 |
Doubling the cover does not quite double the price. A 30 year old woman pays $32 for $500000 and $60 for $1 million. A man pays $38 and $74. Waiting from 30 to 40 raises the price by roughly half. Best Life Insurance for Young Families rewards early buyers.
Another source shows lower prices for the healthiest buyers. LifeStein data from 1 October 2026 shows a man aged 30 at $213 a year. That is for $500000 of cover. A woman pays $182. Those are preferred class rates and the average of the three lowest quotes.
What Smoking Adds to the Price
Tobacco use roughly triples the price. The table compares non-smokers and smokers for $500000 of 20 year term. Both are MoneyGeek averages for average health. Quit before you apply if you can. Insurers may reclassify you after a period without tobacco.
Best Life Insurance for Young Families: Smoker vs Non-Smoker Monthly Cost for $500000
| Age | Woman non-smoker | Woman smoker | Man non-smoker | Man smoker | Man smoker is |
|---|---|---|---|---|---|
| 30 | $32 | $84 | $38 | $119 | 3.1 times |
| 35 | $37 | $111 | $47 | $145 | 3.1 times |
| 40 | $47 | $148 | $59 | $194 | 3.3 times |
The extra cost at 40 for a man is $135 a month. That is $1620 a year. Over 20 years it adds up to $32400. Smoking status is a big price lever in Best Life Insurance for Young Families.
How Long Should the Term Be
One planner suggests a 20 or 30 year level term. Match it to the years your children depend on you. A newborn and a 30 year mortgage point to 30 years. A child aged 10 may need only 15 or 20 years. A term can also end when children finish college.
Some families split cover into two terms. They buy $500000 for 30 years and $500000 for 20 years. Cover falls as needs fall and the cost stays low. One adviser says permanent cover may cost less over a very long term. Weigh that against the price. Term length is a key choice in Best Life Insurance for Young Families.
Top 5 Insurers to Compare
These insurers come from MoneyGeek’s 2026 ranking updated on 23 September 2026. The example is a 40 year old non-smoker with $500000 of 20 year term. Treat the list as a shortlist and not an endorsement. Quotes decide the winner for Best Life Insurance for Young Families.
Best Life Insurance for Young Families: Top 5 Insurers to Compare
| Insurer | MoneyGeek score | AM Best | Woman monthly | Man monthly | Key strength |
|---|---|---|---|---|---|
| Banner Life | 4.5 | A+ | $37 | $46 | Low rates and terms of 10 to 40 years |
| Pacific Life | 4.2 | A+ | $38 | $54 | Many riders and $3 million no-exam limit |
| Nationwide | 4.3 | A+ | $45 | $56 | No-exam up to $1.5 million |
| Protective | 4.1 | A+ | $42 | $54 | Seven term lengths |
| Mutual of Omaha | 4.0 | A+ | $49 | $60 | Top customer satisfaction ranking |
1. Banner Life: Lowest Rates and the Longest Term Range
Banner Life scored 4.5 and holds an A+ rating from AM Best. It offers terms from 10 to 40 years. That suits a family with a newborn. The example price was $37 for a woman and $46 for a man.
It allows up to $10 million of cover and $4 million without a medical exam. Transamerica scored 4.4 with the same example prices. It carries a high complaint index. Banner is a strong start for Best Life Insurance for Young Families.
2. Pacific Life: Many Riders and a High No-Exam Limit
Pacific Life scored 4.2 with an A+ rating. It has the lowest complaint index in the list. It offers many riders. The no-exam limit is $3 million. The example price was $38 for a woman and $54 for a man.
Riders add features to a policy. Ask which riders cost extra. Compare them with the basic policy. This is a feature rich pick for Best Life Insurance for Young Families.
3. Nationwide: Strong No-Exam Option
Nationwide scored 4.3 and holds an A+ rating. It has a strong no-exam option up to $1.5 million. It also has a low complaint index and high customer satisfaction. The example price was $45 for a woman and $56 for a man.
Terms run 10 to 30 years. The maximum cover is $1.5 million. That is enough for many families. Nationwide suits busy parents who want speed in Best Life Insurance for Young Families.
4. Protective: Seven Term Lengths
Protective scored 4.1 and holds an A+ rating. It offers seven term lengths. That helps you match the term to your mortgage. Terms run 10 to 40 years. The example price was $42 for a woman and $54 for a man.
It has no no-exam policy. Expect a medical exam. The process may take longer. The wide choice of terms can still save money. Protective fits families who plan carefully in Best Life Insurance for Young Families.
5. Mutual of Omaha: Top Customer Satisfaction
Mutual of Omaha scored 4.0 and holds an A+ rating. It earned the top J.D. Power satisfaction ranking in the guide. It accepts buyers up to age 80. The example price was $49 for a woman and $60 for a man.
It costs a little more than the others. The brand and service may matter to you. Compare the extra cost with the benefit. Mutual of Omaha is a service focused pick for Best Life Insurance for Young Families.
Features and Riders to Look For
Ask about a conversion option. It lets you switch term cover to permanent cover later. Ask about waiver of premium. It can pause payments if you become disabled. Ask about a child rider. It adds small cover for each child.
Check the insurer’s financial strength. An A rating from AM Best is a good sign. Check the complaint record too. Cover is useless if claims are hard to collect. These checks matter in Best Life Insurance for Young Families.
Cover for a Stay at Home Parent
A parent who stays home does unpaid work. Childcare and cooking and transport would cost money to replace. If that parent died the household would pay for help. Many families overlook this need.
Buy cover on both parents. The stay at home parent usually needs less than the earner. The price is low at young ages. Best Life Insurance for Young Families should protect both adults. Do not leave one parent uncovered.
For Indian Families
The same logic applies in India. One broker estimate covers a healthy non-smoking man aged 30. ₹1 crore of term cover to age 60 costs about ₹1000 to ₹1900 a month. For a woman it is about ₹800 to ₹1600. That page is undated so check a current quote.
Size the cover with DIME or income replacement. Check the insurer’s claim record. Compare at least three quotes. Our India guide covers premiums by age in detail. The method for Best Life Insurance for Young Families does not change by country.
For wider context see the World Economic Forum section on financial and monetary systems. The OECD insurance page explains how insurance protects households from risk. Both add background to Best Life Insurance for Young Families.
5 Costly Mistakes Young Families Make
Mistake 1: Buying Too Little Cover
A small policy leaves a gap. Use DIME or income replacement. Review the number after each child. Best Life Insurance for Young Families should match your real needs.
Mistake 2: Relying Only on Employer Cover
Group cover is often a small multiple of salary. It usually ends when you leave the job. Treat it as a bonus and not a plan. Best Life Insurance for Young Families needs your own policy.
Mistake 3: Choosing a Term That Ends Too Soon
A 10 year term may end before the mortgage does. Pick a term that covers your longest need. Ask about conversion rights. Best Life Insurance for Young Families should outlast the mortgage.
Mistake 4: Hiding Health or Tobacco Facts
A false answer can void a claim. Disclose your history honestly. Honest forms protect your family. Best Life Insurance for Young Families relies on honest answers.
Mistake 5: Waiting for a Better Time
Prices rise with age. Health can change. Buy while you are young and healthy. Delay costs more over time.
Action Plan: Choosing Best Life Insurance for Young Families
Step 1: Add Up Your Needs
List debts and mortgage and education costs. Multiply income by the years your children need support. Subtract savings. That gives your cover amount.
Step 2: Pick a Term Length
Match the term to your mortgage and your children. A 20 or 30 year term is common. Consider splitting the cover into two terms.
Step 3: Get Three Quotes
Ask three insurers for the same cover and term. Compare premium and ratings. Include Best Life Insurance for Young Families picks from the shortlist.
Step 4: Check Riders and Conversion
Ask about conversion and waiver of premium. Ask about child riders. Get the terms in writing.
Step 5: Name Beneficiaries and Review
Name beneficiaries for each policy. Update them after life events. Review your cover every year. Keep documents safe.
Also read: planning an MBA abroad? See Top 10 MBA Universities for International Students 2026: Fees and Scholarship
Frequently Asked Questions
Q1: What is the best life insurance for young families?
For most families level term life is the best choice. It gives large cover at a low price while your children depend on you. A 30 year old woman pays about $60 a month for $1 million per MoneyGeek. A man pays about $74. Best Life Insurance for Young Families usually means a 20 or 30 year term. Compare quotes from several insurers. Check financial strength ratings. Ask about conversion rights. Size the cover from your income and debts. Ask a licensed adviser if you are unsure. Review the policy every year. Keep your beneficiary details current. Do not buy on price alone. Check claim records.
Q2: How much life insurance does a young family need?
It depends on income and debts and the age of your children. Common methods are 10 times income and DIME and income replacement. Our $60000 family needs $600000 by the first method. DIME gives $1.27 million. Best Life Insurance for Young Families should be sized with more than one method. Subtract savings and group cover. Add the cost of college. Count the years until your child is independent. Review the figure after each new child. Round up if you can afford it. Ask a licensed adviser to check the result. Do not guess the number. Write down each assumption. Update it when life changes.
Q3: How much does term life insurance cost for a 30 year old?
MoneyGeek lists a 30 year old non-smoking woman at $32 a month. That is for $500000 of 20 year term. A man pays $38. For $1 million the prices are $60 and $74. These are averages for average health. The healthiest buyers can pay less. Best Life Insurance for Young Families costs more if you smoke. A 30 year old male smoker pays $119 for $500000. Your own quote will differ. Compare several insurers. Answer health questions honestly. Check the term length and the cover amount. Get the quote in writing before you buy. Ask about discounts for higher cover. Check if prices stay level. Compare total cost over the term.
Q4: Does a stay at home parent need life insurance?
Yes. A stay at home parent does work that costs money to replace. That includes childcare and cooking and transport. If that parent died the household would pay for help. Best Life Insurance for Young Families should cover both adults. The price is low at young ages. The cover amount is usually smaller than for the main earner. Estimate what you would pay for help for the years your children need care. Match the term to those years. Get quotes for both parents at once. Ask whether a multi policy discount exists. Review it yearly. Name the right beneficiary for each policy. Keep contact details current. Tell your family where papers are.
Q5: Should young families choose term or whole life insurance?
Most should choose term. One 2026 comparison put whole life at ten times the price of term. That was for a healthy 40 year old. A young family needs large cover for a limited time. Term delivers that at a low price. Best Life Insurance for Young Families is rarely whole life. Whole life can suit lifelong needs such as a child with special needs. It can also suit large estates. Read our comparison guide for the full picture. Ask a licensed adviser about your case. Compare illustrations and fees before you commit. Ask about surrender charges. Ask how loans affect the death benefit. Keep the illustration.
Q6: How long should my term life policy be?
Match the term to the years your family depends on you. One planner suggests a 20 or 30 year level term. A newborn and a 30 year mortgage point to 30 years. An older child may need only 15 or 20. Best Life Insurance for Young Families can also use two terms. You could buy $500000 for 30 years and $500000 for 20 years. Cover then falls as needs fall. Check conversion rights near the end of the term. Get quotes for several term lengths. Compare the price difference between 20 and 30 years. Ask whether the rate stays level. Ask about renewal prices after the term. Plan your next step.
Q7: Do smokers pay more for life insurance?
Yes. MoneyGeek averages show smokers paying about three times as much. A 30 year old man pays $38 a month as a non-smoker. As a smoker he pays $119. The cover is $500000. A woman pays $32 against $84. Best Life Insurance for Young Families is much cheaper if you quit. Insurers may reclassify you after a period without tobacco. Ask each insurer for its rule. Be honest on the application. A false answer can void a claim. Get quotes again after you quit. Check how long you must be tobacco free. Ask whether vaping counts as smoking. Ask about cigars as well. Read the application carefully.
Q8: Can I buy life insurance without a medical exam?
Yes. Some insurers offer no-exam policies with limits. In MoneyGeek’s 2026 list Banner Life allows $4 million without an exam. Pacific Life allows $3 million. Nationwide allows $1.5 million. Protective has no no-exam policy. Best Life Insurance for Young Families can use no-exam cover for speed. Prices may be higher than fully underwritten policies. Compare both options. Answer the health questions honestly. Check the maximum cover and the age limits. Ask whether you can convert or add cover later. Read the policy terms before you pay. No-exam cover can still ask health questions. Some applicants may be sent for an exam. Compare against a fully underwritten quote.
Q9: Which companies offer the best term life insurance?
MoneyGeek’s 2026 ranking scored Banner Life at 4.5 and Transamerica at 4.4. Nationwide scored 4.3. Pacific Life and Fidelity Life scored 4.2. Protective scored 4.1 and Mutual of Omaha scored 4.0. The best choice for Best Life Insurance for Young Families depends on your age. Health and needs matter too. Compare quotes from at least three insurers. Check AM Best ratings and complaint records. Look at riders and term lengths. Prices in the ranking are examples for a 40 year old. Your own quote will differ. Treat the list as a shortlist. Ask each insurer for a written quote. Compare the exact term and cover. Read the exclusions.
Q10: How much does term insurance cost for a young family in India?
One broker estimate covers a healthy non-smoking man aged 30. ₹1 crore of cover to age 60 costs about ₹1000 to ₹1900 a month. For a woman it is about ₹800 to ₹1600. The page is undated so check current quotes. Best Life Insurance for Young Families in India follows the same method. Size the cover with DIME or income replacement. Compare at least three insurers. Check the claim record. Read the exclusions. Disclose your health honestly. Buy early because prices rise with age. Keep your nominee details current. Check the insurer’s claim settlement record. Ask about riders. Compare online and agent prices. Read the policy wording.
Conclusion
Best Life Insurance for Young Families is usually level term life. It gives large cover at a low price while your children depend on you. Size the cover with more than one method. Pick a term that matches your mortgage and your children.
Buy early and avoid tobacco if you can. Cover both parents. Compare three quotes and check ratings and riders. A clear plan for Best Life Insurance for Young Families protects your home.
This guide to Best Life Insurance for Young Families is general information only. It is not insurance or financial advice. Prices and rules change. Confirm all details with a licensed adviser before you buy.
1 thought on “Best Life Insurance for Young Families 2026: Cover Amount and Cost”